Military & VA Home Buying
Military & VA home buying in Eugene, OR requires a plan that works around PCS orders, deployments, assignment lengths, and changing household needs. VA financing may make ownership more accessible for eligible buyers, but a successful purchase still depends on timing, payment comfort, and a clear remote-buying process. This guide is for service members, Veterans, and military households preparing for a Eugene move.
Military & VA Home Buying: How VA Loans Work
A VA-backed loan can help eligible borrowers buy a primary residence with no down payment when they have full entitlement, and it does not require monthly private mortgage insurance. Buyers begin by obtaining a Certificate of Eligibility, or COE, which confirms the VA home loan benefit available to them. The lender still evaluates income, debts, credit, assets, and the property itself.
Eligible borrowers can include active-duty service members, Veterans, qualifying Guard and Reserve members, and some surviving spouses. A private lender funds the mortgage, while the Department of Veterans Affairs guarantees part of the loan. The VA home loan eligibility guidance explains the documentation and service requirements involved.
Buyers should also account for the VA funding fee, which can vary based on benefit use, loan type, down payment, and other factors. Some borrowers may qualify for an exemption, including certain Veterans receiving service-connected disability compensation. Confirm the applicable fee and exemption status with the lender before submitting an offer.
VA loans are intended for owner-occupied homes. PCS orders or deployment may affect when a buyer can occupy the property, so discuss the expected move schedule early.
Military & VA Home Buying: Plan Around PCS Orders
PCS planning works best when buyers organize financing, documents, and decision priorities as soon as orders become likely or arrive. A short timeline does not automatically mean a rushed purchase, but it does require dependable communication and a clear sequence of decisions.
Start with the date housing is needed, the anticipated assignment length, and whether the entire household will arrive together. Update preapproval information, collect pay and asset documents, and ask the lender how remote signatures, identity verification, and schedule changes will be handled. Basic Allowance for Housing can be part of the income picture, but it should not become the entire housing budget.
Buying before arrival can offer more control over move-in timing and reduce the need for temporary housing. It also requires confidence in the location, property condition, and contract terms. Buying after arrival allows for in-person visits and a better understanding of daily routines, though it may mean renting first.
Before making a remote offer, decide who can review properties, coordinate access, and communicate quickly if travel or duty obligations interrupt the process. Establishing those roles before the search begins can keep deadlines manageable.
Choosing a Eugene Location for Daily Life
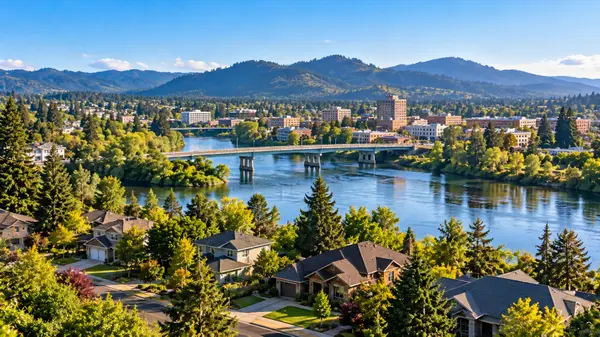
The right Eugene location should support your household routine, expected commute, and anticipated length of stay. Eugene is a city in Lane County, and buyers benefit from evaluating how a location functions during ordinary weekdays rather than selecting solely from a map.
For military households relocating to the region, travel time can change with peak-hour traffic, weather, school schedules, and the route used. Test likely routes at the times you would normally travel when possible. Consider access to groceries, health care, outdoor recreation, childcare, and services that may matter when one household member is managing daily responsibilities during travel or deployment.
Neighborhood fit also depends on the home itself. A lower-maintenance property may suit a shorter assignment or frequent travel, while additional storage, an extra bedroom, a flexible work area, or outdoor space may matter more for a longer stay. Review parking, utility expectations, maintenance history, and the age of major systems.
A location that works well on the first visit should also make sense for a normal weekday. Consider how the home supports routines, not only how it appears during a brief showing.
First-Time Buyer Essentials for Military Households
A first-time buyer budget should include the full cost of ownership, not only the mortgage payment. Plan for principal and interest, property taxes, homeowners insurance, utilities, maintenance reserves, and any applicable homeowners association dues. Basic Allowance for Housing can help support the payment, but a workable budget should still leave room for savings, household costs, and a future move.
Preapproval should happen early because it provides a realistic price range before the home search becomes emotionally demanding. A lender reviews income, assets, debts, credit, and VA eligibility factors. Loan approval does not necessarily mean every payment level will remain comfortable through travel, career changes, or assignment transitions.
Earnest money is a deposit submitted after an offer is accepted and handled under the purchase agreement. Closing costs are separate expenses that may include lender, title, recording, and prepaid items. VA rules limit some charges that buyers may pay, and sellers may be able to contribute toward allowable costs when the contract and lender requirements permit it.
Keep cash reserves after closing whenever possible. Even without a required down payment, ownership comes with expenses that are easier to handle when the household has room in its budget.
Buying on a Short Timeline
A remote purchase can work when communication, documentation, and decision authority are organized before a suitable home appears.
| Item to coordinate | Practical approach |
|---|---|
| Virtual showings | Request live video walkthroughs that include the exterior, street setting, storage, major systems, and visible concerns. |
| Offer timing | Establish how quickly you can review listings, authorize an offer, and respond to contract deadlines. |
| Communication | Set regular update times and identify a backup contact if travel, orders, or time-zone changes interrupt communication. |
| Remote closing | Confirm lender-specific procedures for secure documents, notarization, signatures, and final funds. |
Buy or Rent After a PCS?
Buying may fit a PCS move when the expected stay, monthly payment, and future exit plan align. Renting first may provide more flexibility when assignment length is uncertain, or the household needs time to learn Eugene’s daily patterns.
| Decision point | Buying may fit when | Renting first may fit when |
|---|---|---|
| Expected timeline | You expect enough time to settle in and prepare for a future sale or rental strategy. | Future orders or assignment length remain uncertain. |
| Home search | You can evaluate homes carefully through visits or detailed remote due diligence. | You need more time to understand routes, property types, and routines. |
| Monthly payment | The full ownership cost leaves room for savings and unexpected expenses. | A purchase would reduce flexibility or stretch the household budget. |
| Future move | You have considered resale, maintenance, vacancies, and possible rental management. | You prefer a simpler exit plan when the assignment ends. |
VA Appraisals and Home Inspections Have Different Roles
A VA appraisal is not a home inspection because the two processes answer different questions. The appraisal helps the lender assess value and determine whether the property meets VA minimum property requirements. A home inspection gives the buyer a more detailed assessment of condition, maintenance needs, and visible concerns that may require further evaluation.
A buyer can use a VA loan without obtaining a private home inspection, but an inspection is still strongly recommended. It can identify issues involving major systems, safety, deferred maintenance, and components that may need specialist review. That information gives buyers a clearer understanding of the home beyond its estimated value.
The appraisal may identify property conditions that affect VA financing, but it does not offer the same scope as an inspection. The VA appraisal guidance explains that an appraisal is not a guarantee of value or a substitute for a buyer’s independent evaluation.
Military buyers should leave enough time in the contract process to review findings, ask questions, and decide whether the property supports their budget and move schedule. This is particularly important when the purchase is being managed from another location.
Thinking Ahead to Your Next Move
Military & VA home buying should include an exit plan before the offer is written. If you later sell the home and pay off the VA loan, entitlement may be restored for a future purchase. Keeping the property as a rental can also be possible after occupancy requirements are met, but it may affect the entitlement available for another VA loan.
Robin Troy, the “Paw'Sitive Realtor,” is a licensed Oregon REALTOR® serving Eugene and Lane County buyers. Call (541) 914-0214 or email rtroyis@gmail.com for help coordinate a VA-financed purchase and remote closing around PCS orders.
FAQ
Is Eugene a good place to live?
Eugene can be a good fit for households that value outdoor access, a mix of established neighborhoods, and access to education and health care employment. The best location depends on your commute, budget, preferred home type, and the daily routines you expect during your assignment.
Is Eugene expensive?
Eugene’s costs vary significantly by housing choice, household size, and lifestyle. The aggregate reported home-sale median in the Eugene postal-city area was $475,000 as of July 2026 (Attom Data, as of 2026-07), so buyers should evaluate the total monthly ownership cost rather than focus only on a purchase price.
What salary do you need in Eugene?
The income needed to buy in Eugene depends on the home price, interest rate, monthly debts, property taxes, insurance, and available savings. A lender can review documented income, including eligible military compensation, and translate it into a realistic purchase range.
Can I use my VA loan more than once?
Eligible borrowers can use VA loan benefits more than once. Entitlement may be restored after a VA-financed home is sold and the loan is paid off, although the details depend on the previous loan and remaining entitlement.
Do I need a down payment with a VA loan?
Eligible buyers with full entitlement may be able to purchase with no down payment. A down payment can still be useful when entitlement is reduced or when the buyer wants to lower the loan amount and possible funding fee.
Can I buy a home before I arrive at my new duty station?
Yes, buyers can complete a purchase before arriving when remote tours, financing, document handling, and contract deadlines are carefully coordinated. Live video walkthroughs, detailed questions, and a clear communication plan make a long-distance decision more manageable.
Does a VA loan require a home inspection?
No, a VA loan does not require a private home inspection. An independent inspection remains a wise step because it provides a more detailed view of condition and potential maintenance needs than a VA appraisal.
Categories
Recent Posts
GET MORE INFORMATION